
When it comes to giving your business a quick financial boost, a small business loan isn’t your only option. We explain what a business line of credit is and how it could suit your goals.
At a glance
- A business line of credit is a set credit limit your business can draw on, repay and use again as needed, with no new application each time.
- The facility is committed, so it stays open between draws, with a periodic check-in rather than a fresh approval every time you need funds.
- It suits the gaps in everyday cash flow, like covering wages before invoices are paid or stocking up ahead of a busy season, rather than the single planned purchase a business loan is built for.
When you’re comparing funding options, it helps to start with the costs you’re covering. A one-off purchase you can see coming suits a loan. Wages due before the invoices are paid, or stock to buy before the season starts, can call for a business line of credit, with one approval and ongoing access to funds.
What is a business line of credit?
A business line of credit is a flexible, revolving credit facility that gives your business ongoing access to a set pool of funds. You draw what you need up to an approved limit, repay it, and draw again as often as required. Interest is charged only on the amount you’ve drawn, so an undrawn limit accrues no interest.
Banks and online lenders both offer business lines of credit, with limits that reach $500,000 with a lender like Prospa. Because the limit refreshes as you repay, it suits recurring, hard-to-predict costs over a one-off purchase. And a committed facility like Prospa’s Business Line of Credit is designed to stay open, ready for whatever the month brings.
How does it work in practice?
You apply once, the lender assesses your business, and you’re approved for a credit limit. The limit is a ceiling to draw against as needed, not a sum paid out on day one. With Prospa, applying takes about 10 minutes online, and you can access up to $150,000 with no property security upfront, assessed on how your business is performing rather than what it owns. That approach is known as cash flow lending.
From there the cycle is draw, repay, redraw. You take out what the week or month calls for, and every dollar repaid frees up to draw again, with no paperwork in between. Speed varies by lender; Prospa drawdowns are instant through the Prospa App or Prospa Online, with no reassessment at the moment you need the money.

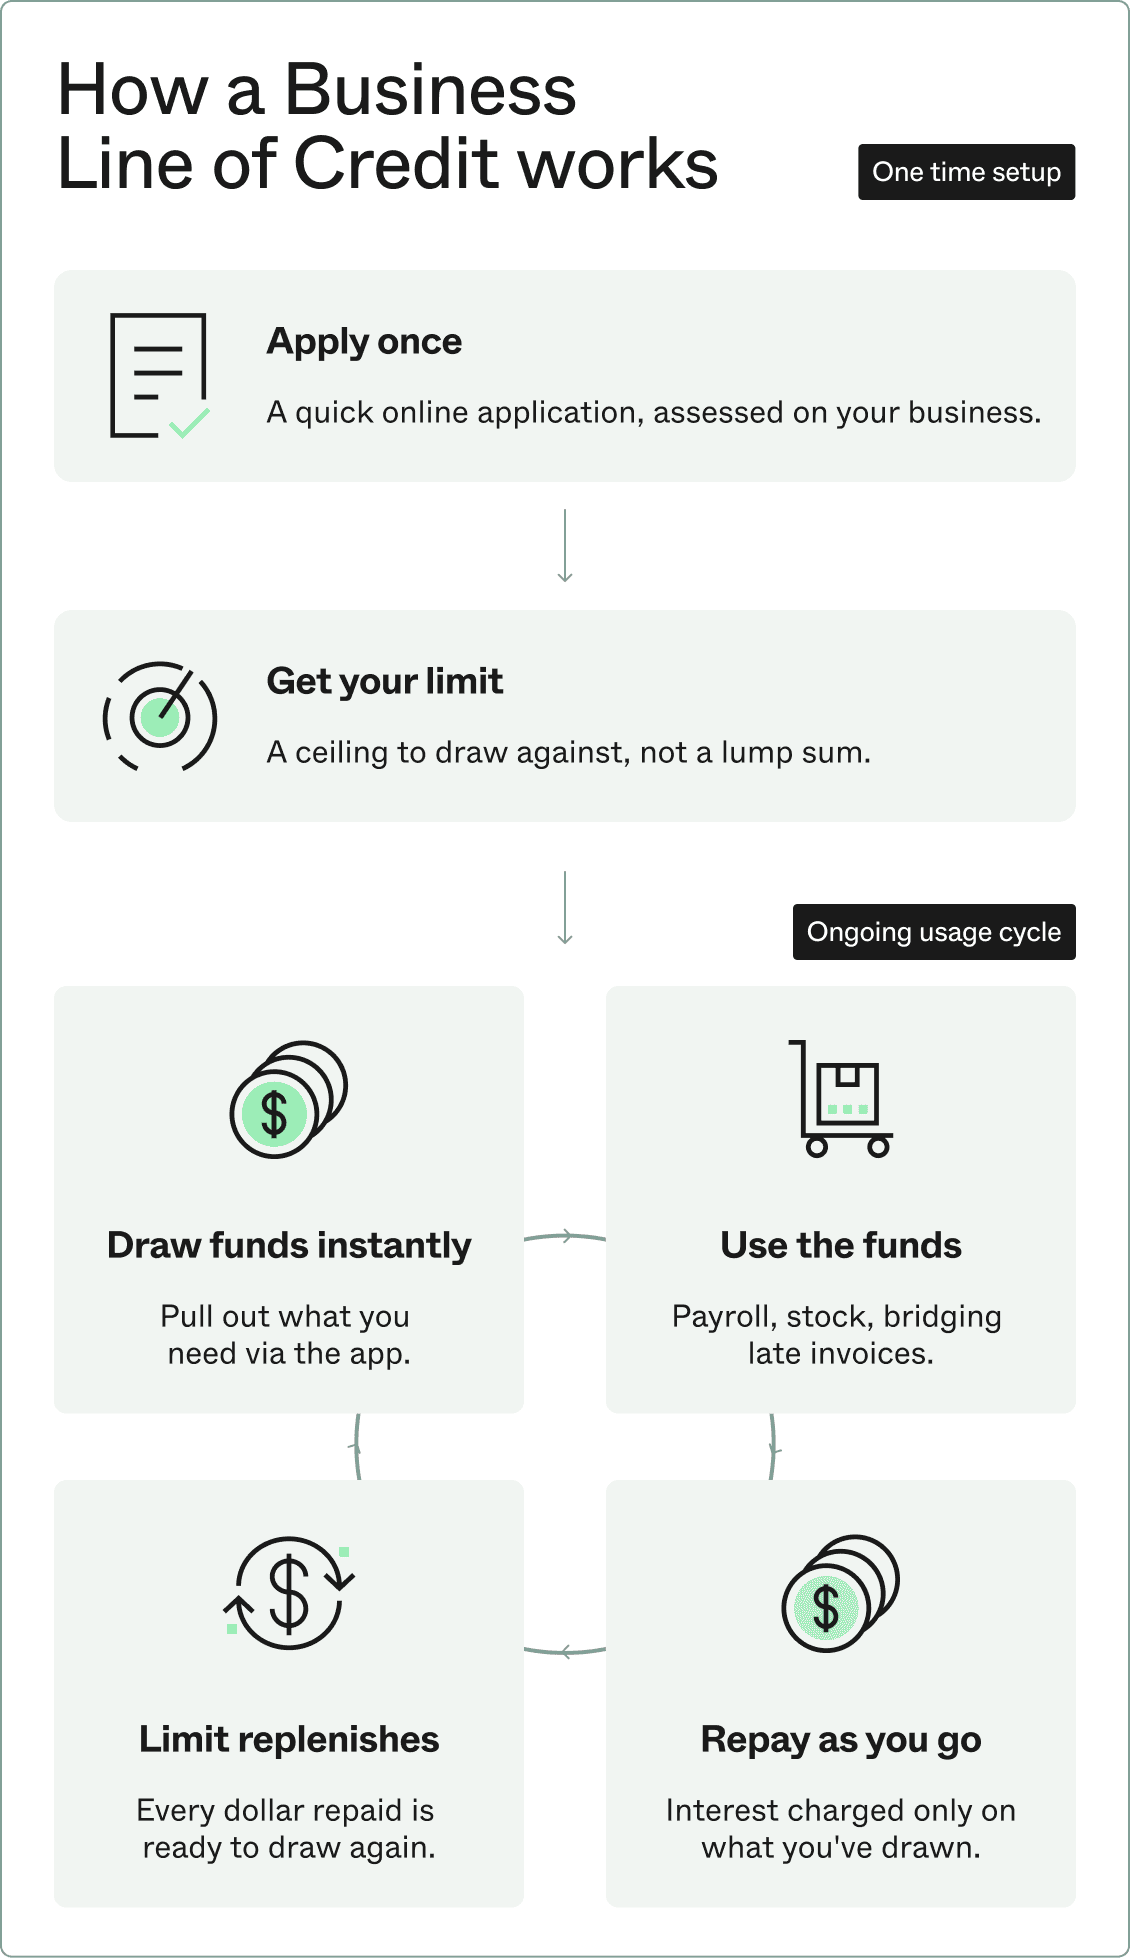
Interest and fees. Interest is charged on the balance you’ve drawn, not on your full limit, so an undrawn limit accrues no interest. Most lenders also charge an ongoing fee for keeping the facility available, so compare products on both numbers. Prospa charges a fixed rate on drawn funds, calculated daily, plus a weekly service fee of 0.046%, which on a $30,000 facility works out to under $2 a day, with no origination fee. To see repayments and total interest for your scenario, run the numbers through Prospa’s calculator and select Line of Credit on the product toggle.
A committed line of credit is built to stay open rather than re-approved at every draw. Prospa checks in every two years, and if the eligibility criteria are still met, the facility automatically continues.
Line of credit or business loan?
A loan is the better fit when you know the number. Buying a vehicle, fitting out a new site, taking on a project with a fixed quote: you borrow the amount, repay it over an agreed term, and the facility closes when it’s paid. A line of credit trades that certainty for ongoing access, keeping the funds available once you’ve repaid.
| Business line of credit | Business loan | |
|---|---|---|
| Structure | A revolving limit you draw, repay and reuse | A one-off lump sum |
| Interest | Charged on the drawn balance only | Charged on the full amount borrowed |
| Repayments | Flex with how much you’ve drawn | Fixed over a set term |
| Best for | Ongoing, unpredictable cash flow needs | A single, planned purchase |
| Access | Refreshes as you repay | Ends once the loan is repaid |
For a fuller breakdown, including how repayments and total cost compare, read Prospa’s guide to business loan vs line of credit.
What can you use a business line of credit for?
A business line of credit puts the timing in your hands. You choose when to draw and how much, so you can take a supplier discount the day it’s offered or cover a shortfall the week it opens up, with no new approval in the way. With Prospa, you can also pay invoices and suppliers straight from your Business Line of Credit in the Prospa App, without drawing the funds down to your own account first. And because what you repay is what you pay for, the facility costs you in proportion to the funds you use.
Most businesses use one for the weeks when money has to go out before it comes in:
- Covering wages when client payments are still weeks away, or when GST, payroll and supplier bills land together
- Buying stock ahead of a busy season or to lock in a bulk discount
- Paying suppliers on time to protect terms and relationships
- Bridging quieter months without dipping into personal funds
Because the limit refreshes, a line of credit is easier to lean on than a fixed loan, so it works best when you have a plan for paying down what you draw. Steady repayments also keep your credit score healthy. Fees apply for ongoing access however much you draw, and interest adds up if a balance stays out for months. It fits businesses with regular cash flow movement more than one-off borrowing.
Is it the same as a business overdraft?
No. A business line of credit and a business overdraft serve the same purpose: having funds available when a cost lands before the cash to cover it. The main difference is the way they’re built, which affects when and how you use them.
| Business line of credit | Business overdraft | |
|---|---|---|
| Structure | A standalone facility with its own credit limit | An extension of your business transaction account |
| How you access funds | Draw down and send funds wherever they’re needed | Spend past a zero balance on that account |
| When you can use it | Whenever you like, without your account being overdrawn | Only once the account dips below zero |
| Interest and fees | Interest on the drawn balance; with Prospa the rate is fixed and there’s no origination fee | Interest on the overdrawn amount, usually at a variable rate, often with an establishment fee |
There are other alternatives to an overdraft worth comparing, and the right one usually depends on what’s creating the shortfall.
Who can apply?
Every lender sets its own bar, usually around trading history, turnover and the strength of your cash flow. For a Prospa Business Line of Credit, you’ll need at least two years of trading history, monthly turnover of $6,000 or more, and a valid NZBN (sole traders can apply without one).
No property security is required upfront to access up to $150,000, and provided you keep meeting your obligations, it won’t be required later either. For facilities above $150,000, you’ll need to provide security over your business assets. Prospa does ask for a personal guarantee on all funding, which is a commitment from the business owner or directors to repay what the business borrows.
What’s involved in getting a business line of credit?
The process is online with most lenders, and quicker than many owners expect. With Prospa, it takes about 10 minutes.
- Check you meet the basics. Confirm you’ve been trading at least two years, with monthly turnover of $6,000 or more.
- Gather your details. Have your NZBN, business details and recent business bank statements ready, or verify your bank information securely online for a faster decision.
- Apply online. Complete the application on Prospa’s Business Line of Credit page, or speak with a Business Lending Specialist if you’d like to talk it through first.
- Get a decision. For funding up to $150,000, a response often comes within the hour if you verify your bank details online, or within a business day if you upload statements; larger facilities take around 2 to 3 days.
- Draw when you’re ready. Once you’ve signed, funds can reach your account in as little as an hour, and from then on you draw through the Prospa App, repay as you go, and reuse the limit as needs arise.
Find out more and apply for a Prospa Line of Credit – applying takes 10 minutes and funding is possible in hours on approved applications.